Quick Answer
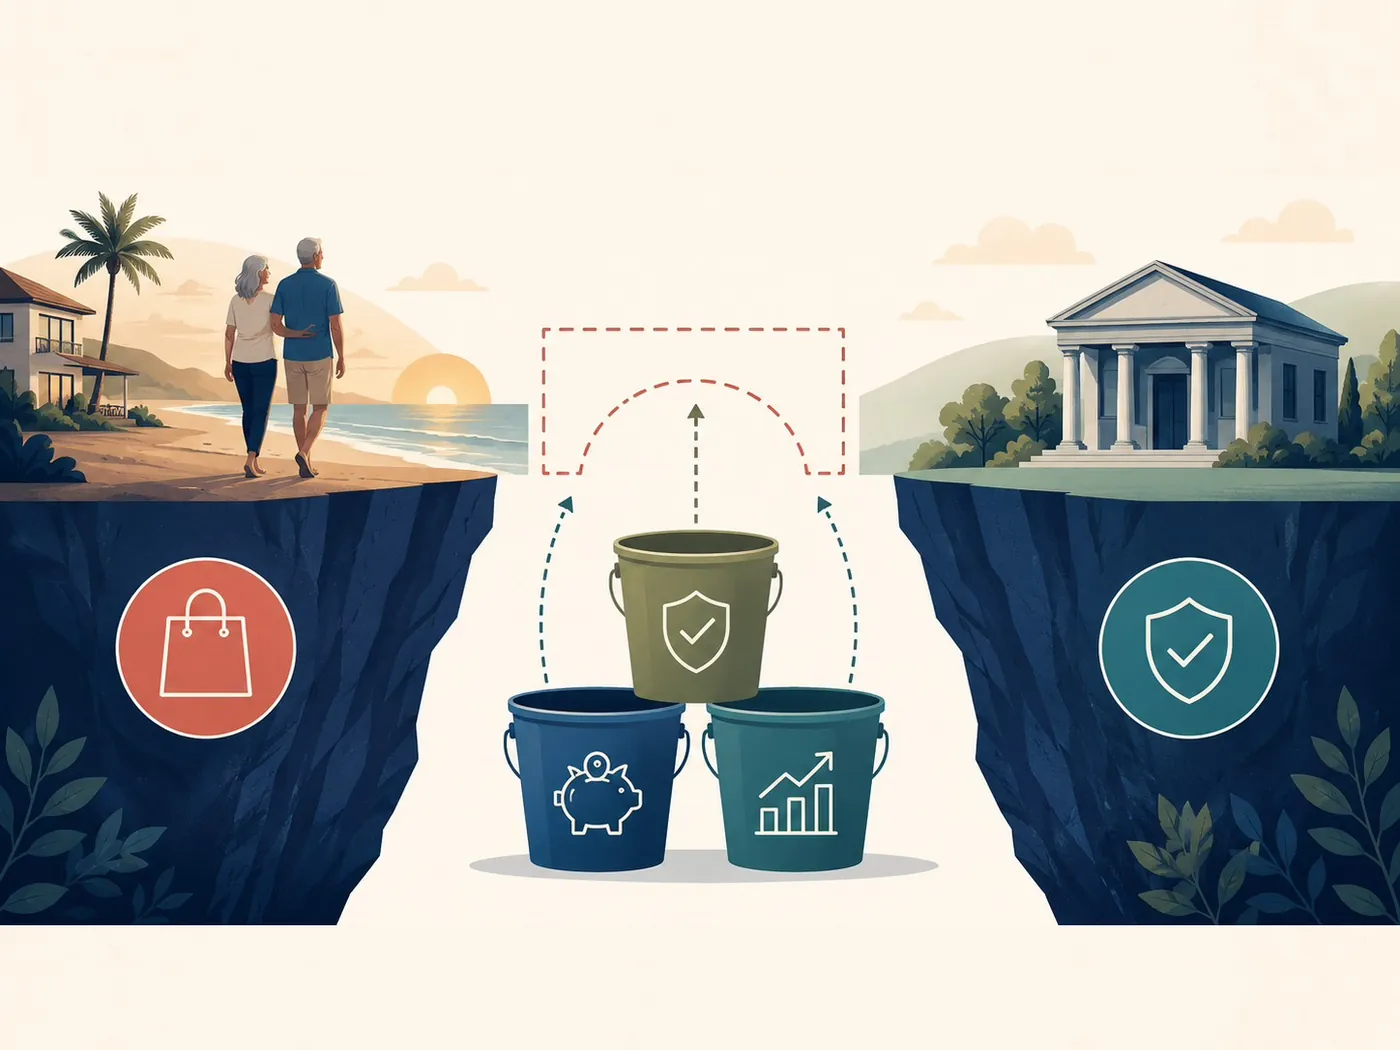
Your retirement income gap is the amount your savings and investments need to provide after reliable income is subtracted from spending.
The basic formula is:
Retirement income gap = monthly spending target - reliable monthly income
Reliable monthly income may include Social Security, pensions, annuities, rental income, or part-time work. The gap is usually filled by cash, taxable investments, traditional IRAs, 401ks, Roth accounts, and other assets.
The real calculation should also include taxes, healthcare, inflation, debt payments, one-time expenses, RMDs, and survivor planning.
The AI Retirement Income Planner looks at the same gap from the other side. You set how much each account pays in each phase of retirement, and it shows what is left to spend after tax and healthcare, how much of that is guaranteed income, and whether each phase reaches the target you set. Then you can test how the choice of account affects taxes, healthcare costs, balances, confidence, and stress-test results.
Why The Income Gap Matters
Many retirement questions are really income-gap questions.
Examples:
- Can I retire at 60?
- Should I claim Social Security at 62?
- Can I delay Social Security until 70?
- Do I need part-time work?
- Which account should I withdraw from first?
- How much cash should I keep?
- Can I afford healthcare before Medicare?
- Will I run out of money?
All of these depend on the same core issue:
How much money needs to come from savings each month?
Investor.gov explains that many workers now rely on defined contribution plans, where employees bear investment risk and there is no guarantee the account balance will be adequate for retirement. That makes the income-gap calculation important. A large account balance can still feel fragile if the monthly gap is too large.
Step 1: Calculate Monthly Spending
Start with spending, not savings.
List current monthly expenses:
- Housing
- Utilities
- Food
- Transportation
- Insurance
- Healthcare
- Debt payments
- Taxes
- Home maintenance
- Travel
- Hobbies
- Gifts
- Charitable giving
- Family support
Then add expenses that do not happen every month.
Examples:
- Property taxes
- Homeowners insurance
- Car insurance
- Vacations
- Vehicle replacement
- Home repairs
- Dental work
- Major medical costs
- Annual subscriptions
- Holiday gifts
Convert those annual or irregular expenses into a monthly amount.
Example:
- Monthly bills: $5,600
- Annual property taxes and insurance: $8,400
- Annual travel budget: $9,600
- Home and vehicle reserve: $6,000
Annual irregular expenses total $24,000, or $2,000 per month.
Estimated monthly spending target:
$5,600 + $2,000 = $7,600
That $7,600 is the first draft of the monthly retirement spending target.
Step 2: Separate Essential And Flexible Spending
Not every expense has the same importance.
Group spending into:
- Essential spending
- Important but adjustable spending
- Flexible lifestyle spending
Essential spending includes housing, utilities, food, insurance, healthcare, debt payments, and taxes.
Flexible spending may include travel, hobbies, gifts, upgrades, and optional purchases.
This matters because the income gap can be managed in hard years if some spending can adjust.
Example:
- Essential spending: $5,400 per month
- Flexible spending: $2,200 per month
- Total spending target: $7,600 per month
If markets fall, the household may be able to reduce flexible spending for a year or two without cutting essentials.
Step 3: Add Reliable Income
Next, list income that does not require selling investments.
This may include:
- Social Security
- Pension income
- Annuity income
- Rental income
- Part-time work
- Spouse income
- Disability income
- Other recurring income
Social Security timing can change the gap, and when to take Social Security compares the ages side by side. SSA says retirement benefits can be claimed anytime between age 62 and 70, and the payment is higher the longer you wait up to age 70. SSA also says you can check your Social Security account to estimate benefits at different claiming ages.
Example:
- Social Security at 62: $2,870 per month
- Social Security at full retirement age (67): $4,100 per month
- Social Security at 70: $5,080 per month
The same household may have three different income gaps depending on claiming age.
Step 4: Calculate The Monthly Gap
Now subtract reliable income from spending.
Example:
- Monthly spending target: $7,600
- Social Security: $3,800
- Pension: $1,200
- Reliable monthly income: $5,000
Monthly income gap:
$7,600 - $5,000 = $2,600
That means savings and investments need to provide about $2,600 per month before considering taxes, healthcare timing, inflation, and one-time expenses.
Annual gap:
$2,600 x 12 = $31,200
The $31,200 annual gap is the starting withdrawal need.
Step 5: Add Taxes
The withdrawal need and the spending need are not always the same.
If the gap is filled from a traditional IRA or 401k, the withdrawal may be taxable. If it is filled from taxable investments, capital gains may apply. If it is filled from Roth accounts, qualified withdrawals may be tax-free. If it is filled from cash, the cash may not create income, although interest may be taxable.
Example:
- Spending gap: $31,200 per year
- Source: traditional IRA
- Estimated effective tax on extra withdrawal: 15%
The household may need more than $31,200 withdrawn to spend $31,200.
Approximate gross withdrawal:
$31,200 / 0.85 = $36,706
This is why retirement income planning should focus on spendable income after taxes.
Step 6: Include Healthcare Timing
Healthcare can change the income gap by age.
Before Medicare, HealthCare.gov says retirees who lose job-based coverage before age 65 can use the Marketplace to buy a plan. HealthCare.gov also says premium tax credits and lower out-of-pocket costs depend on income and household size.
That means retirement withdrawals can affect healthcare costs before age 65. IRA and 401k withdrawals generally count as income for Marketplace purposes.
After Medicare begins, costs still matter. Medicare.gov says what you pay for Medicare depends on coverage choices, services, and providers. For 2026, Medicare.gov lists the standard Part B premium as $202.90 per month, or higher depending on income.
Your income-gap plan should show separate healthcare assumptions for:
- Pre-Medicare years
- Medicare enrollment year
- Medicare years
- Higher-healthcare-cost years
- Long-term care risk
Step 7: Decide Which Accounts Fill The Gap
Once you know the gap, decide which account funds it.
Possible sources:
- Cash
- Taxable brokerage account
- Traditional IRA
- 401k or 403b
- Roth IRA
- Roth 401k
- HSA for qualified healthcare expenses
- Annuity payments
- Home equity, if part of the plan
The source matters because it can affect:
- Federal taxes
- State taxes
- Social Security taxation
- ACA Marketplace income
- Medicare IRMAA
- RMDs
- Cash reserves
- Survivor planning
- Estate goals
A simple withdrawal order may work for some households. Other households need a blended strategy.
Example:
- Cash covers the first year of the gap
- Taxable investments cover early retirement years
- Traditional IRA withdrawals fill low-tax years
- Roth accounts are preserved for high-tax years or survivor planning
- HSA funds are used for qualified medical expenses
A good model shows how each withdrawal source changes the long-term plan.
Step 8: Watch The Gap Before Social Security Starts
The income gap is often largest before Social Security and pensions begin. That stretch has its own article: how much can I spend in retirement works through the spending side of the same question.
Example:
- Retire at 62
- Delay Social Security until 70
- Pension begins at 65
- Medicare begins at 65
The plan has several stages:
- Ages 62 to 64: no Social Security, no pension, pre-Medicare healthcare
- Ages 65 to 69: pension begins, Medicare begins, Social Security delayed
- Age 70 and later: Social Security begins and the gap shrinks
The early gap may be large, but temporary.
That is different from a permanent gap.
Look at the gap phase by phase, or year by year, instead of relying on a single average.
Step 9: Watch The Gap After RMDs Begin
Later in retirement, RMDs can change the gap again.
The IRS says required minimum distributions are minimum amounts that many retirement plan and IRA account owners must generally withdraw each year. Traditional IRAs, SEP IRAs, SIMPLE IRAs, and retirement plan accounts are subject to RMD rules. Roth IRA owners are not required to take lifetime RMDs.
RMDs can help fund the income gap, but they can also create more taxable income than the household needs for spending, which is the subject of how RMDs change your retirement tax bill.
Questions to model:
- When do RMDs begin?
- Are RMDs larger than the spending gap?
- Do RMDs increase taxable Social Security?
- Do RMDs affect Medicare IRMAA?
- Should Roth conversions be tested before RMDs begin?
- What happens to the surviving spouse?
RMDs are part of the income plan even before they start.
Step 10: Add One-Time Expenses
A clean monthly gap can hide large future costs.
Add known or likely expenses:
- Vehicle replacement
- Roof replacement
- Major home repair
- Moving costs
- Family support
- Weddings
- Medical procedures
- Dental work
- Long trips
- Tax payments
- Funeral costs
Example:
- Monthly income gap: $2,600
- Annual gap: $31,200
- Vehicle replacement in year 3: $35,000
That year's real gap is not $31,200. It is closer to $66,200 before taxes and account-source effects.
The AI Retirement Income Planner keeps these out of the monthly average. On the Lump sums tab, each one-time cost lands at the start of the phase you assign it to, paid from the account you choose, and the tax that withdrawal creates is charged with it.
Step 11: Stress Test The Gap
The income gap should be tested under pressure.
Stress tests may include:
- Market decline in the first 3 years
- Higher inflation
- Higher healthcare costs
- Lower Social Security than expected
- Pension reduction or loss
- Part-time work ending early
- Large home repair
- Long-term care event
- One spouse dying earlier than expected
- Longer life than expected
A plan with a $2,600 monthly gap may look fine in normal conditions. It may look different if the portfolio falls 20% early in retirement while healthcare costs rise.
Stress testing shows whether the gap is manageable or too fragile.
The planner covers part of that list directly. Its Stress test tab combines different investment returns with different inflation rates, the historical backtest on the Confidence tab replays every starting year on record, bad ones included, and the survivor scenario on What-if? covers a spouse dying earlier than expected. The rest, such as higher healthcare costs or part-time work ending early, are changes you make to a copy of the plan and then compare.
Example: A Retirement Income Gap Calculation
Assume a couple is age 63 and 61.
They have:
- Monthly spending target: $7,800
- Essential spending: $5,500
- Flexible spending: $2,300
- Cash and taxable savings: $180,000
- Traditional IRAs and 401ks: $900,000
- Roth accounts: $120,000
- HSA: $25,000
- Social Security if both claim as early as they can (at 63 and 62): about $3,900 per month combined
- Social Security if both delay to 70: about $6,600 per month combined
- Pension beginning at 65: $1,400 per month
- Marketplace healthcare before Medicare
They test three scenarios.
Scenario A: Claim Social Security Now
Reliable income begins sooner.
The monthly income gap is smaller in the first years, but Social Security benefits are lower for life.
Scenario B: Delay Social Security And Use Taxable Savings
The early income gap is larger.
Cash and taxable accounts fall faster, but future Social Security income is higher.
Scenario C: Delay Social Security And Work Part-Time
Part-time income reduces the gap during the bridge years.
The plan depends on the work actually happening, so they also test what happens if part-time income ends early.
The best answer depends on taxes, healthcare, cash reserves, survivor planning, and stress-test results.
How To Use The AI Retirement Income Planner
Use this workflow:
- Work out your monthly spending target and your essential spending, as in Steps 1 and 2.
- On the My Goals card in Edit values, turn goals on and enter the target as Target net income and your essentials as the Minimum income floor. Both are in today's money, after tax and healthcare.
- Add Social Security, pensions, part-time work, and rental income under Income streams and in each phase. An annuity can be added to the plan from the Annuities tab.
- Enter account balances. The planner has four account types: 401k or IRA, cash, taxable investments, and Roth. An HSA has no place of its own.
- Check the healthcare assumptions in Edit values. The planner estimates ACA premiums before 65 and Medicare Part B and D after, and healthcare costs can inflate at their own rate.
- Set how much each account pays in each phase. That choice is how you fill the gap, and the planner works out the tax on it for you.
- Open Plan Health. The Income Goal check names any phase that falls short of your target, says by how much, and suggests which withdrawal would close it.
- On the Drawdown tab, choose Floor & Upside to see guaranteed income beside the portfolio gap, phase by phase.
- Add one-time costs on the Lump sums tab.
- Test claiming ages on the SS Optimizer tab, or with the Social Security slider on What-if?.
- Check RMD Compliance in Plan Health. The planner estimates RMDs from your birth year and flags any phase whose 401k withdrawal falls short of them.
- Test the plan under pressure with the Stress test tab, the Monte Carlo and historical views on the Confidence tab, and, if you are married, the survivor scenario on What-if?.
- Keep alternatives in Saved plans and use Compare to set one beside the plan on screen.
The goal is to move from a vague question to a visible plan:
"Here is the gap, here is where the money comes from, and here is what happens if conditions change."
Retirement Income Gap Checklist
Before retiring, review:
- Monthly spending target
- Annual irregular expenses
- Essential spending
- Flexible spending
- Social Security estimates
- Pension income
- Part-time income assumptions
- Rental or business income
- Healthcare before Medicare
- Medicare costs
- Taxes
- Account balances by tax type
- Withdrawal order
- Cash reserve
- Debt payments
- One-time expenses
- RMD timing
- Roth conversion opportunities
- Inflation assumptions
- Market stress tests
- Survivor income gap
Common Income Gap Mistakes
Mistake 1: Using Gross Income Instead Of Spendable Income
Taxes can reduce what is available for spending. Estimate after-tax income.
Mistake 2: Averaging The Gap Across Retirement
The gap may be large before Social Security and smaller later. Year-by-year planning is better than a single average.
Mistake 3: Ignoring Healthcare Before Medicare
The pre-Medicare healthcare bridge can create a larger income gap than expected.
Mistake 4: Forgetting One-Time Expenses
Vehicle purchases, home repairs, and medical costs can change the gap in specific years.
Mistake 5: Treating All Accounts The Same
Cash, taxable investments, traditional IRAs, Roth accounts, and HSAs can have very different tax effects.
Mistake 6: Skipping Survivor Planning
The surviving spouse may have a different income gap, tax status, healthcare cost, and withdrawal need.
FAQ
What is a retirement income gap?
A retirement income gap is the difference between retirement spending and reliable retirement income. Savings and investments usually need to fill that gap.
How do I calculate my retirement income gap?
Add monthly spending, including irregular annual expenses converted to a monthly amount. Then subtract reliable income such as Social Security, pensions, annuities, rental income, or work income.
Should taxes be included in the income gap?
Yes. A $3,000 monthly spending gap may require more than $3,000 of withdrawals if the money comes from taxable retirement accounts.
Does healthcare affect the income gap?
Yes. Healthcare before Medicare, Medicare premiums, out-of-pocket costs, prescriptions, dental, vision, and hearing costs can all affect the gap.
Can Social Security eliminate the gap?
Sometimes. In other cases, Social Security covers only part of the spending need. Claiming age can change the gap, so compare several claiming ages.
What if my income gap is too large?
Possible adjustments include working longer, working part-time, reducing spending, delaying Social Security, changing withdrawal order, downsizing, paying off debt, using annuities, or revising retirement timing.
Should I use cash or IRA withdrawals to fill the gap?
It depends on taxes, healthcare income thresholds, RMDs, Social Security taxation, Medicare IRMAA, Roth accounts, and cash reserve needs. Compare more than one withdrawal order.
Sources
- Investor.gov, Managing Lifetime Income: https://www.investor.gov/additional-resources/retirement-toolkit/managing-lifetime-income
- Social Security Administration, Plan For Retirement: https://www.ssa.gov/retirement/plan-for-retirement
- HealthCare.gov, Health Coverage For Retirees: https://www.healthcare.gov/retirees/
- Medicare.gov, Medicare Costs: https://www.medicare.gov/basics/costs/medicare-costs
- IRS, Retirement Plan And IRA Required Minimum Distributions FAQs: https://www.irs.gov/retirement-plans/retirement-plan-and-ira-required-minimum-distributions-faqs
- IRS Publication 590-B, Distributions From Individual Retirement Arrangements: https://www.irs.gov/forms-pubs/about-publication-590-b
Educational Disclaimer
This article is for general education only. It is not financial, tax, investment, legal, healthcare, insurance, Social Security, Medicare, estate, or retirement advice. Tax rules, benefit rules, healthcare costs and thresholds change over time, and any projection depends on assumptions that may not hold. Screenshots show a sample plan with invented figures and are illustrative only. Verify important figures with official sources such as IRS.gov, SSA.gov, Medicare.gov and HealthCare.gov, and confirm decisions with a qualified professional before acting.